Newsletter issue
The regime, the five findings, and what to watch this week: 26 October 2026
A precautionary rotation. The index fell while most stocks rose, software took over from chips, and oil replaced AI as the worry. The Fed meets Wednesday.
Last updated
Hi,
Here is the week in three parts. The kind of market we are in, the findings that mattered most, and what to pay attention to next. The three reports behind it are at the bottom.
The regime
The index went down and most stocks went up. That is the whole week in one line.
The S&P 500 closed at 7,623 on Friday, its second weekly loss in a row, and the Nasdaq fell for a second week too. Yet the typical stock in my core universe rose 1.2 percent and 62 percent of them finished higher. The gap is the biggest AI names. Meta fell 9.4 percent and Alphabet 6.0 percent, and because the index weights the giants, their losses outweighed everyone else's gains.
This was precautionary, not a vote of confidence. Money came out of the crowded AI names and the metals and went to the places that hold up better if the AI spending story cracks and oil keeps rising: software, regional banks, housing, biotech and energy. Thursday's move came on a sharp fall in bond yields and reversed within the day. Friday's came on oil, after another tanker strike in the Strait of Hormuz pushed Brent to 116.72 dollars, its highest settle since April. Neither was the kind of move where investors add risk across the board.
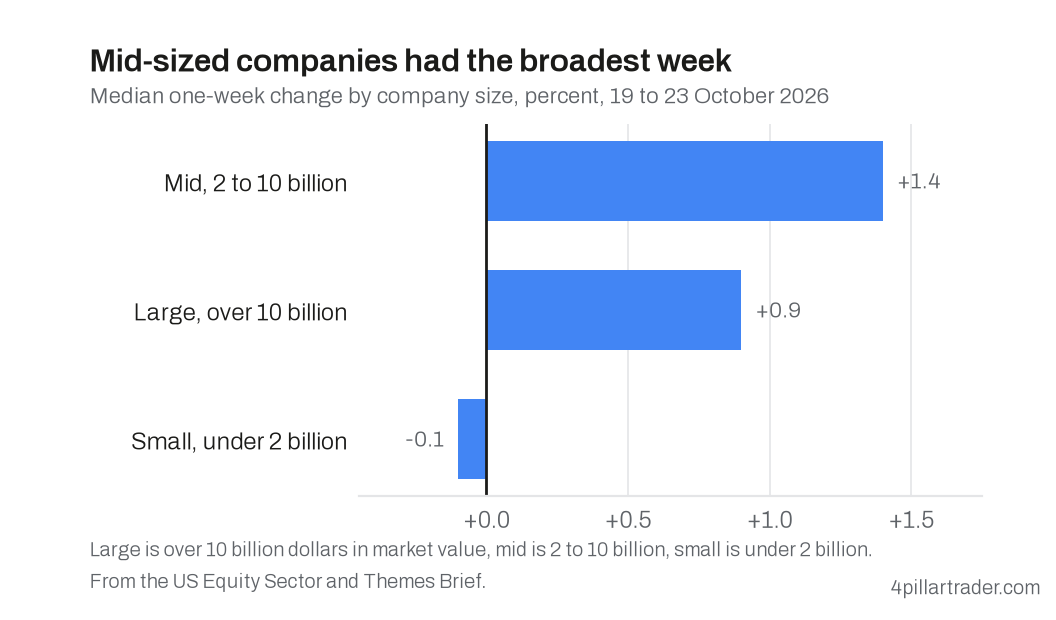
In plain terms. This was not a broadening and it was not a selloff. It was investors taking precautions. They stopped leaning on a handful of AI names and spread their risk around, which shows up as a falling index while most stocks rise. Spreading risk is not the same as adding it.
The five findings that mattered
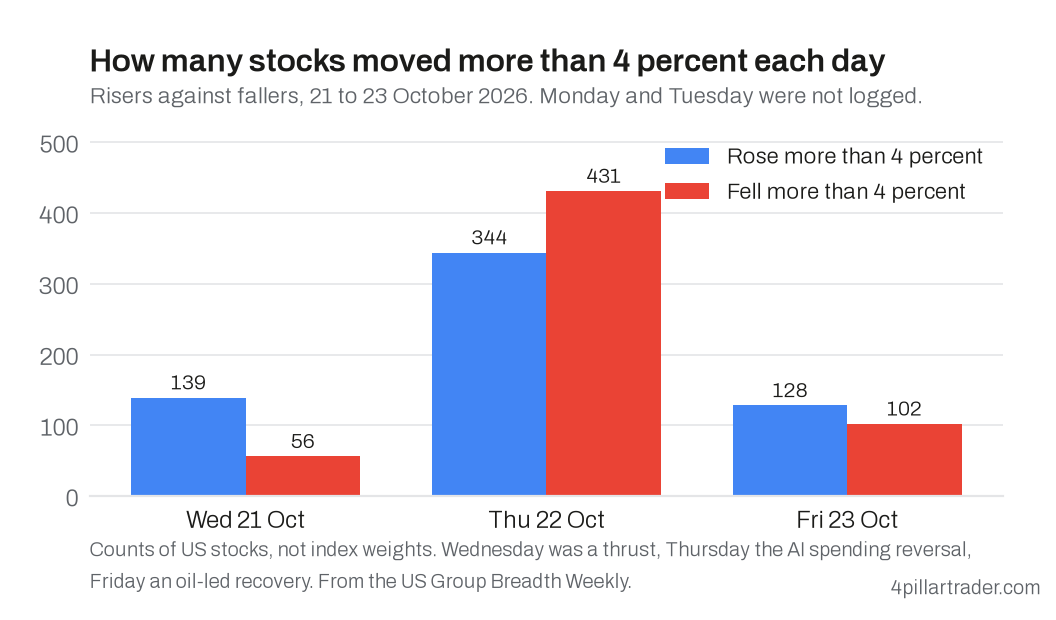
1. Breadth flipped from washout to thrust. Last week, for every stock that rose more than 4 percent on a day, two and a half fell. This week the count was 611 risers against 589 fallers across the three sessions logged, a ratio of 1.04 against 0.39. Wednesday was a genuine thrust with 139 risers to 56 fallers. Thursday reversed hard as the AI spending worry hit, 344 to 431. Friday recovered, 128 to 102, on energy and cybersecurity. Read the better numbers as positioning rather than conviction. Thursday showed how fast the thrust unwound the moment the AI spending worry hit. The detail is in the group breadth weekly.
2. Inside technology, leadership moved from chips to software. The typical software stock rose 5.8 percent on the week with 82 percent of names up. The typical semiconductor fell 1.8 percent. On Friday cybersecurity led the whole market after a broker survey pointed to bigger security budgets and serious flaws were disclosed in PHP, the language behind most websites. Seventeen infrastructure software names rose more than 4 percent and none fell. The sector table is in the sector and themes brief.
3. On Friday, oil replaced AI as the main worry. Brent rose 3.1 percent to 116.72 dollars, up 6.2 percent on the week, and US crude went back above 100. Energy was the one sector with broad gains, 89 percent of names up, and supplied 49 of the 122 companies that rose more than 4 percent. Thursday's defensive winners reversed: consumer staples had no risers and eleven fallers, consumer discretionary three against eighteen. Only 35 percent of stocks rose on the day. Friday's movers brief has every name.
4. Bond yields dropped, bounced, and settled right at 5 percent. The 10-year yield, the rate almost everything else is priced off, fell 18 basis points on Thursday and gave about 5 back on Friday to close the week at 5.00 percent. Regional banks, housing and mortgage lenders rallied on Thursday's drop and faded as yields rose again. Traders put about 71 percent odds on a December rate rise going into the Fed.
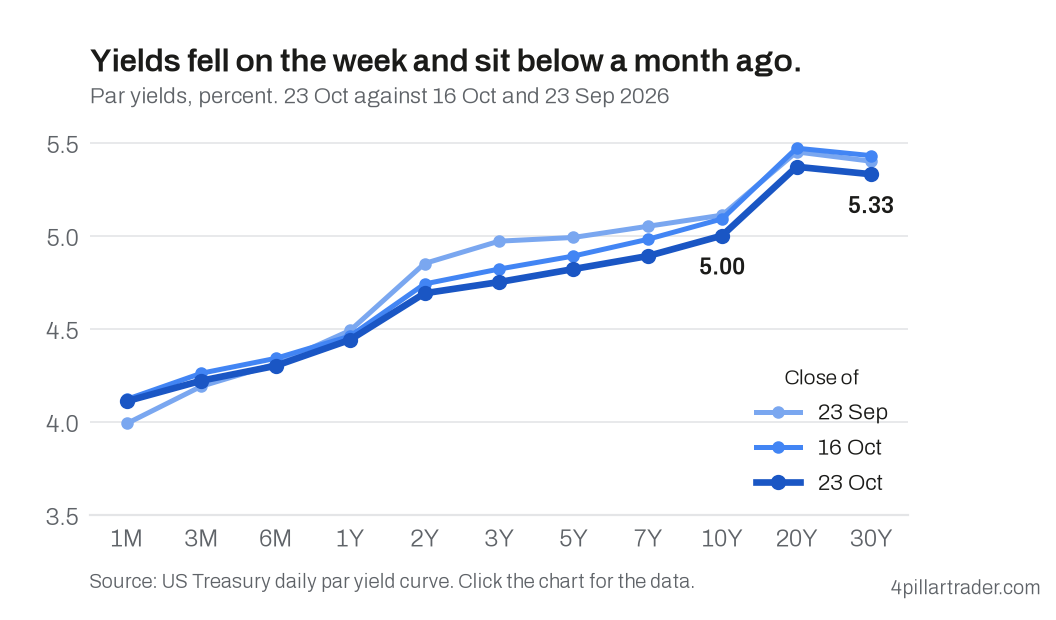
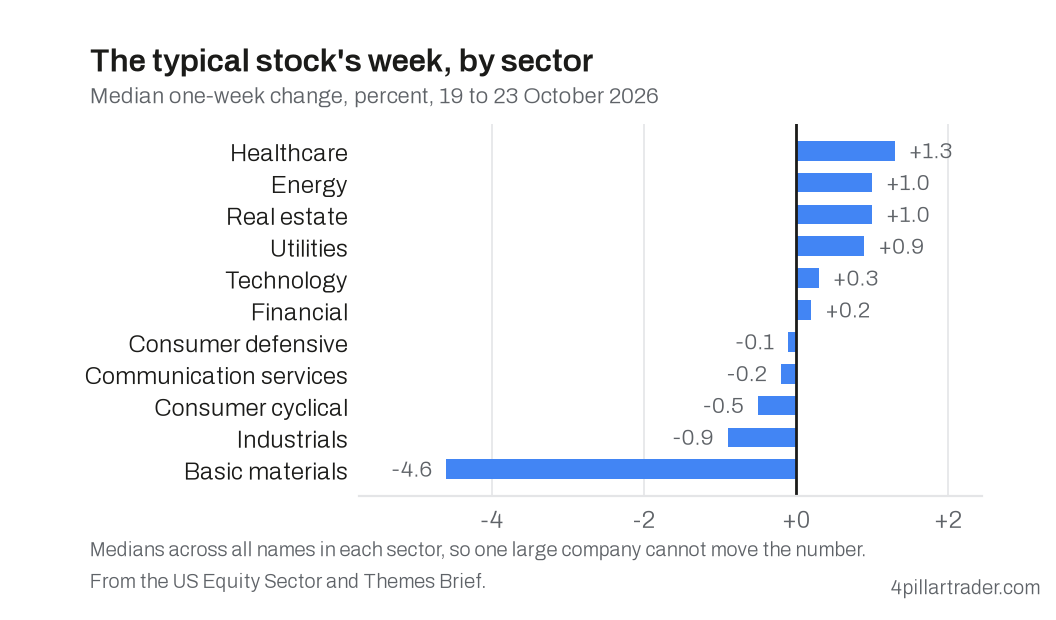
5. Metals and miners were the weakest group in the market, and households are gloomy. Not one precious-metal miner in the core universe rose on the week and none is above its 50-day average. Basic materials fell 4.6 percent at the median, the worst sector by a distance. Meanwhile consumer sentiment finished October at 48.0 and households expect 4.7 percent inflation over the next year. Oil feeding into inflation expectations is the thing that keeps the Fed leaning towards higher rates.
What to pay attention to next
Each of these is a question with a clear answer coming.
- The Fed on Wednesday 28 October. The meeting runs 27 and 28 October and a hold is widely expected. What matters is whether the statement firms up December. A hawkish tone that pushes the 10-year back above 5 percent would undo the rate-sensitive bounce.
- Microsoft and Alphabet on 28 October. Both report Wednesday. After Meta, the question is capital spending and whether cash flow covers it. Strong guidance could pull money back from software into AI hardware. Weak guidance spreads the Meta reaction.
- Software holding its gains. More than 70 percent of software names are above their 50-day average. If that holds through the Microsoft and Alphabet results, it is leadership rather than a place to hide.
- Energy if Brent stalls. Friday was a single-session, headline-driven move. A second day of broad gains across drillers, services and producers would make it leadership. If Brent stops rising and the group fades, it was a spike. Any de-escalation with Iran pulls crude sharply lower.
- Growth and inflation on Thursday 29 October. The first estimate of third-quarter GDP and September's PCE inflation, the Fed's preferred price gauge, land the morning after the Fed.
- Semiconductor breadth. Chips stabilised on Friday after a heavy week. If their breadth recovers on the mega-cap earnings, Thursday's AI selling was a one-session shock. If it does not, the worry is spreading from the builders to the chips, and the precautionary money stays where it went.
- The midterms on 3 November and the next CPI on 10 November. The October consumer price report arrives after the election and before the Fed's December meeting.
This week's reports
Three PDFs, free, observation rather than advice. Email services do not carry attachments, so each one downloads from the site.
[[FILE: US Equity Sector and Themes Brief | /pdf/us-equity-sector-themes-brief-2026-10-23.pdf | Which sectors, industries and themes gained or lost ground over the week, with the catalyst behind each move labelled confirmed or narrative.]]
[[FILE: US Movers and Catalysts, Friday 23 October | /pdf/us-movers-catalysts-2026-10-23.pdf | Every stock that moved more than 4 percent on Friday, grouped by industry, with the reason where there was one.]]
[[FILE: US Group Breadth Weekly | /pdf/us-group-breadth-weekly-2026-10-19.pdf | How many stocks rose or fell more than 4 percent each day, by industry group. The clearest picture of how broad the week was.]]
That is the week. If one of these needs more explaining, hit reply and tell me which.
Speak soon,
The 4 Pillar Trader
4pillartrader.com
P.S. I'm a 4 Pillar Trading affiliate. If you join through my link I earn a commission.
Data as of: Prices to Friday 23 October 2026, US close. Daily breadth covers three of the five sessions.
Weekly newsletter
Get the next issue in your inbox
That was one week's issue, exactly as it went out. Subscribe and the next one comes to you, with subscriber-only offers as they come. Unsubscribe in one click.
About the newsletter and every past issue →
The newsletter is educational and general in nature. It is not personal financial advice. See the financial disclaimer.