Newsletter issue
Chips broke, oil fell, gold miners rose. The week and what is next: 9 November 2026
A post-election rally, then the worst day for chips since 2020. The index fell 2.7 percent but the typical stock finished flat. Inflation Tuesday.
Last updated
Hi,
Here is the week in three parts. The kind of market we are in, the findings that mattered most, and what to pay attention to next. The three reports behind it are at the bottom.
The regime
One election, two violent days, and a week that looked worse on the index than it was underneath.
Tuesday's midterms gave Democrats both chambers of Congress. On Wednesday the S&P 500 rose 1.6 percent and the Dow 3 percent, the S&P's best day in three months, and oil fell hard on hopes of an end to the war with Iran. On Thursday the AI trade came apart. The Nasdaq fell 5.5 percent, the S&P 500 4.4 percent and the chip index 12 percent, on fears that the election result slows the permits and power that data centres need. Friday bounced.
For the week, the S&P 500 fell 2.68 percent and the Nasdaq 3.37 percent, their worst week since June. Yet the typical stock in my core universe finished flat, with half of them higher. The damage sat in two places, technology and energy. Money went to gold miners, airlines, builders and hospitals: things that gain from cheaper oil, lower rates, or a change in Washington.
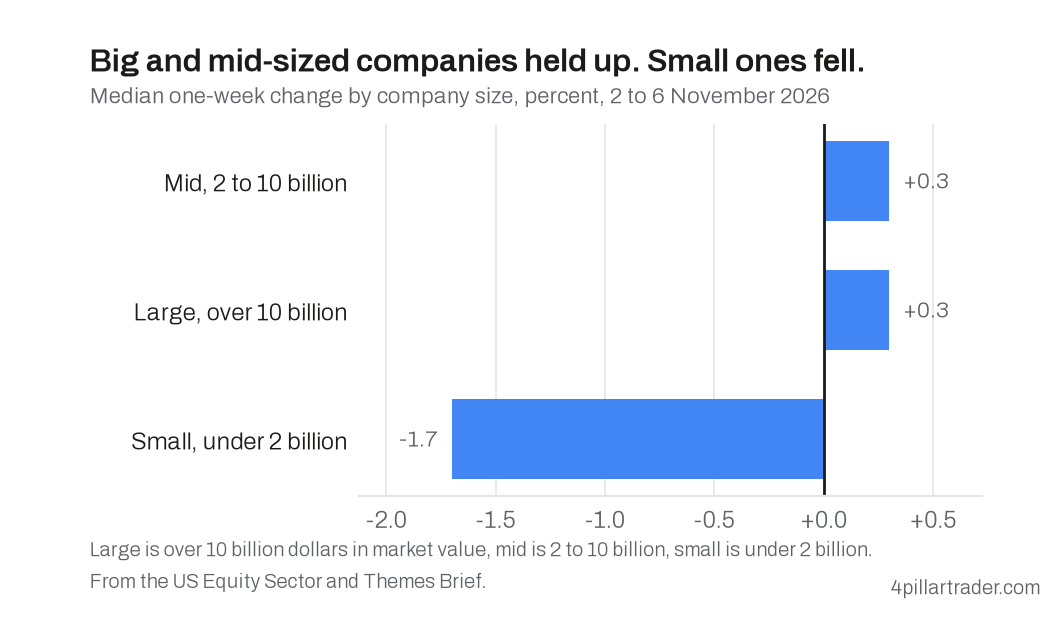
In plain terms. This is a precautionary market that just lost its two leaders in one week. The biggest AI names were sold on a policy fear, oil was sold on a peace hope, and the money moved to safer, domestic groups rather than leaving the market.
The five findings that mattered
1. Thursday was the worst day for chips since 2020, and the trigger was policy, not sales. Across chips and AI hardware, 114 names fell more than 4 percent on Thursday and 1 rose that much. Qualcomm fell 19 percent and AMD and Micron 17 percent. UBS warned that pauses could put about 30 percent of planned 2028 data-centre capacity at risk. Economists expect the result to slow data-centre building and raise its cost. Friday's bounce lifted 71 of 73 core chip names, but the group is still down 10 percent on the week and 28 percent on the month.
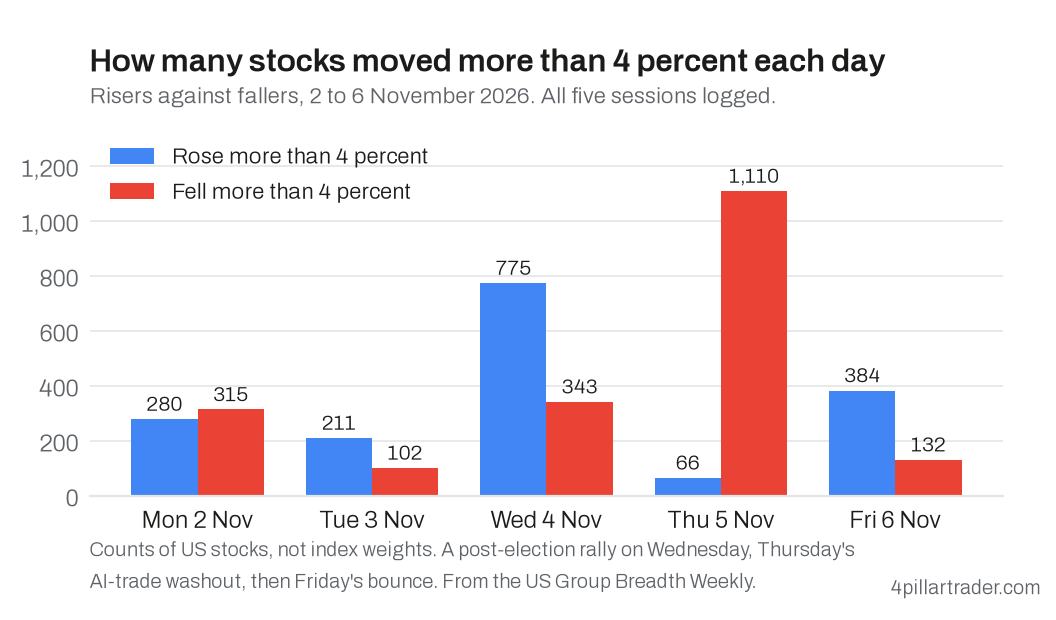
2. The breadth swung harder than at any point in my log. On Wednesday 775 stocks rose more than 4 percent. On Thursday 66 rose and 1,110 fell that much, a ratio of 0.06, the lowest reading I have. On Friday 384 rose and 132 fell. Over five sessions 1,716 rose against 2,002 that fell. The day-by-day counts are in the group breadth weekly.
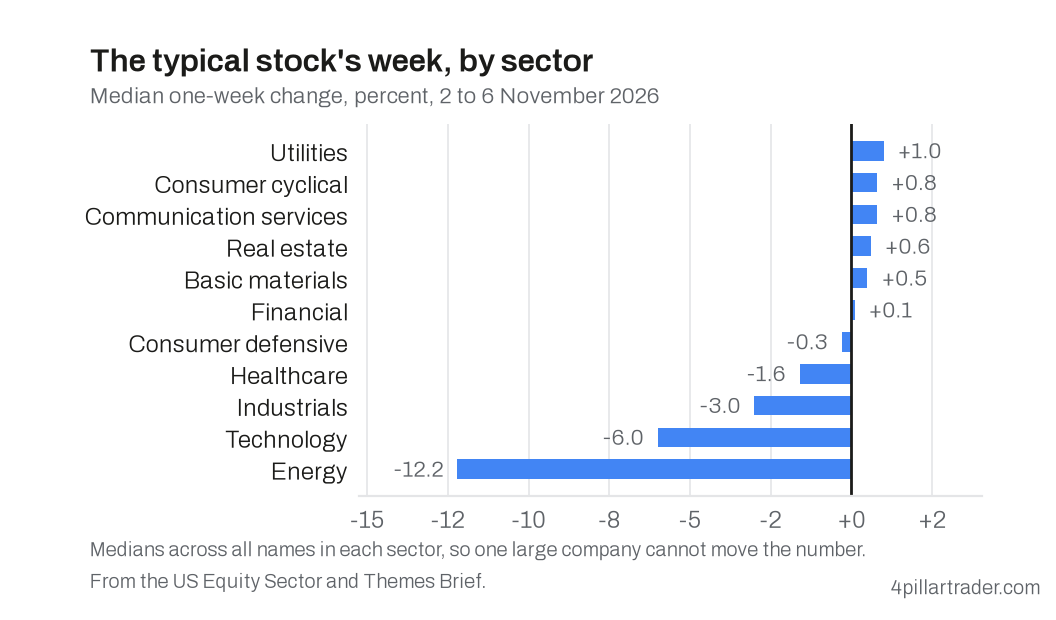
3. Oil had its steepest week in years and broke energy. Brent, the global oil price, fell about 13 percent on the week to near 98 dollars as the vote raised hopes of an end to the Iran war. US crude settled at 90.83 dollars on Friday. The typical energy stock fell 12.2 percent and only 4 percent of them rose. Not one oil and gas producer in my core list finished up. Cheaper fuel went straight to the users: airlines rose 9.9 percent with 12 of 13 up on Friday. The detail is in the sector and themes brief.
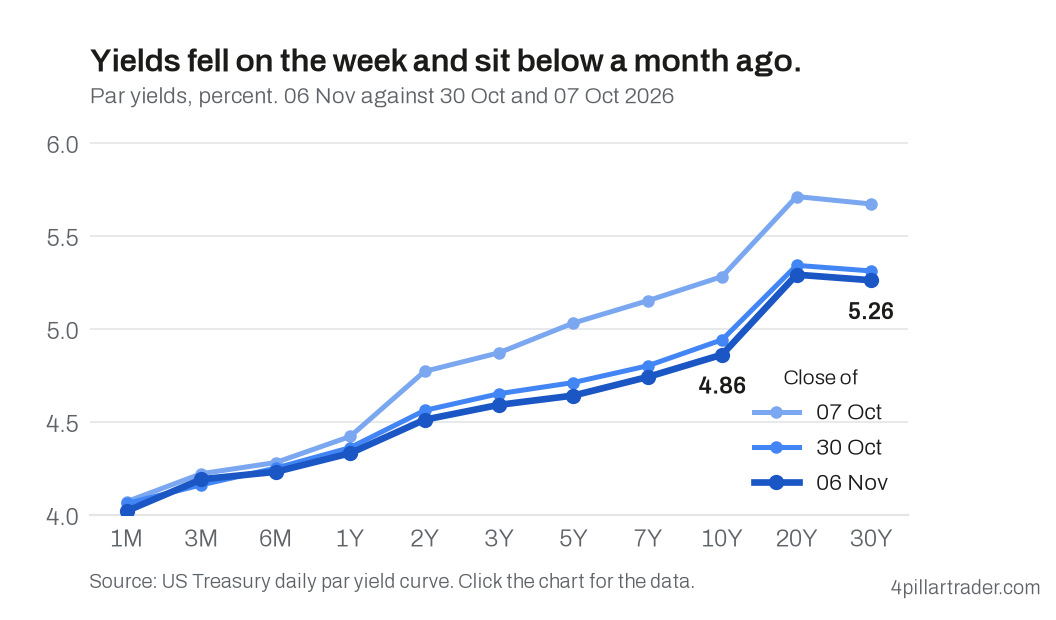
4. Jobs beat by a mile, and a December rate rise is back as the main case. October payrolls rose 165,000 against forecasts near 60,000 to 65,000, and unemployment fell to 4.1 percent. The official release has the detail. Treasuries fell as traders added to bets on a December rise. The 2-year yield, the one most tied to the Fed, rose to 4.51 percent on Friday. Over the week, though, the 10-year yield, the rate almost everything else is priced off, fell 0.08 percentage points to 4.86 percent, helped by Thursday's rush into bonds.
5. Gold miners flipped from losers to the strongest group in the market. Gold rose about 3 percent on Wednesday, back above 4,000 dollars, as the dollar slid after the result. All 44 precious-metal miners in my core list rose on the week, a median gain of 13.3 percent, and they held up on Thursday when almost nothing else did. They had spent the previous three weeks on the losing side. Friday's movers brief has the day's names.
What to pay attention to next
Each of these is a question with a clear answer coming.
- Inflation on Tuesday 10 November. Economists expect consumer prices to show 3.9 percent inflation, up from 3.7 percent. The October report lands at 8.30 in the morning. Does a hot number on top of the jobs beat lift the 2-year further and test the gold miners?
- Chips, second day. Friday's bounce came from the most beaten names. Do the large chip makers hold above Thursday's lows for a second week, or does Thursday get retested?
- CoreWeave on Tuesday, Applied Materials and Cisco on Thursday. These three report this week. They are the first read on data-centre spending since the vote.
- Oil and the Iran talks. US crude is near 91 dollars. Does it stay below 95, or does a setback in talks lift it and turn energy and the airlines around?
- Producer prices on Friday 13 November. The October producer price report shows what companies pay. Company calls mentioned inflation more in October than any month since early 2024.
- Wednesday's havens. Health care, staples and insurers were sold on Friday. Does that selling continue, which would mean money leaving the market rather than rotating inside it?
- The Fed on 8 and 9 December. The December meeting is the last of the year. This week's two price reports decide how much a rise is already expected.
Where I stand
I am staying cautious. One bounce after a day with 1,110 fallers does not repair the damage, and the groups that led the market into this week are the ones that broke.
What I am paying attention to is relative strength. That means which groups held their ground on Thursday when almost everything fell, and which were still rising on Friday when the broken names bounced. Gold miners, airlines and the builders passed that test. Chips, energy and software did not. Strength that survives a bad day tells you more than a big bounce after one.
That is how I am reading it. It is observation, not advice.
Want the process behind this?
Everything above comes from one way of working: read the macro backdrop, find what the money is doing underneath the index, pick the groups and companies worth researching, and size any position so a week like this one cannot hurt you. That is the four-pillar process, and it is what 4 Pillar Trading teaches live, with mentors who have institutional experience, in a community where ideas get pulled apart in the open.
The trial is 19 dollars for 30 days through my link. Cancel before day 31 and that is all you pay. Pricing and inclusions are set by 4 Pillar Trading and can change, so confirm the current terms on their page before you commit.
Affiliate link. I earn a commission if you join through it, at no extra cost to you. My full review sets out the limitations alongside the strengths.
This week's reports
Three PDFs, free, observation rather than advice. Email services do not carry attachments, so each one downloads from the site.
[[FILE: US Equity Sector and Themes Brief | /pdf/us-equity-sector-themes-brief-2026-11-06.pdf | Which sectors, industries and themes gained or lost ground over the week, with the catalyst behind each move labelled confirmed or narrative.]]
[[FILE: US Movers and Catalysts, Friday 6 November | /pdf/us-movers-catalysts-2026-11-06.pdf | Every stock that moved more than 4 percent on Friday, grouped by industry, with the reason where there was one.]]
[[FILE: US Group Breadth Weekly | /pdf/us-group-breadth-weekly-2026-11-02.pdf | How many stocks rose or fell more than 4 percent each day, by industry group, and which themes switched sides during the week.]]
That is the week. If one of these needs more explaining, hit reply and tell me which.
Speak soon,
The 4 Pillar Trader
4pillartrader.com
P.S. I'm a 4 Pillar Trading affiliate. If you join through my link I earn a commission.
Data as of: Prices to Friday 6 November 2026, US close. Daily breadth covers all five sessions.
Weekly newsletter
Get the next issue in your inbox
That was one week's issue, exactly as it went out. Subscribe and the next one comes to you, with subscriber-only offers as they come. Unsubscribe in one click.
About the newsletter and every past issue →
The newsletter is educational and general in nature. It is not personal financial advice. See the financial disclaimer.